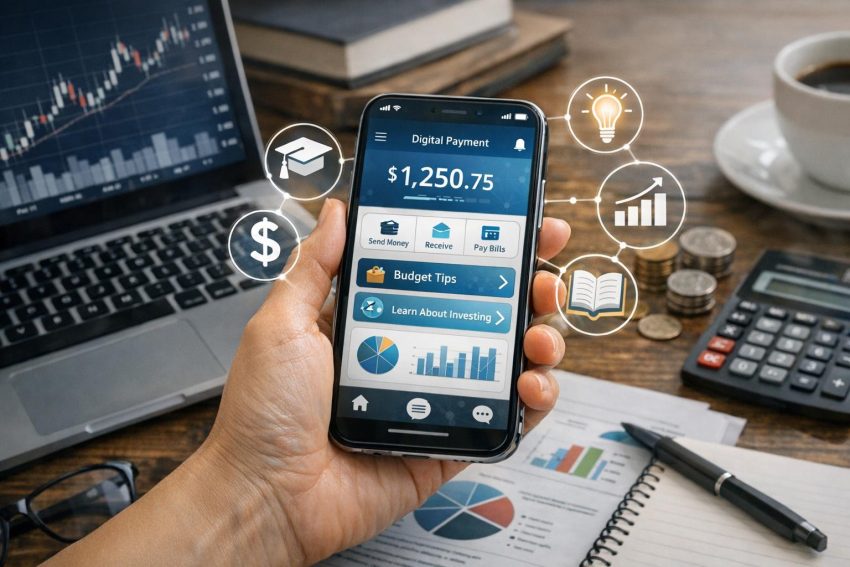
Digital payment platforms now sit at the centre of routine financial activity. Mobile wallets, banking apps, contactless cards, online checkout services, peer-to-peer transfers, remittance apps and instalment payment providers let people receive, hold and spend money without using cash. Although speed and convenience remain their main commercial purpose, these platforms can also teach users how money moves and how daily choices affect personal finances.
Financial education covers the knowledge and practical skills used to manage income, expenses, savings, credit, fees, risk and future obligations. Schools, employers, banks, consumer groups and public agencies have traditionally delivered such education through lessons, workshops and printed guidance. Payment platforms add a practical channel because they can present relevant facts while a user is checking a balance, reviewing a purchase or deciding whether to borrow.
This timing matters. General advice about controlling expenses may feel remote from daily life. A notice showing that recurring subscriptions cost £85 a month is harder to ignore. Likewise, a repayment screen showing the full cost of an instalment plan can connect an abstract lesson about interest with an immediate purchasing decision.
Digital payments do not automatically improve financial knowledge. An app can make spending almost effortless while explaining very little about fees, debt or data use. Its educational value depends on clear wording, fair interface design, accurate records and prompts that help rather than pressure the user. The business model behind the service matters too. A provider paid each time a customer borrows or spends may have different priorities from an educator trying to improve household financial health.
How Payment Activity Can Become Financial Education
Digital platforms turn many financial actions into records. Cash users can usually see how much remains in a purse or wallet, but reconstructing a month of cash purchases takes discipline and a pile of receipts. Digital transactions normally create a searchable history containing the date, amount, merchant and payment method. Some services also assign each purchase to a category.
A transaction record is not a lesson on its own. Its value appears when the platform helps a user interpret it. A monthly summary may show that small convenience purchases cost more than a utility bill. A chart might reveal that weekend spending regularly exceeds weekday spending. A subscription list can show payments that continue long after the user stops using a service.
These records connect actions with outcomes. The customer sees the purchase, the reduced balance and its effect on the money available for later commitments. Low-balance notices, scheduled payment reminders and weekly spending reports can reinforce that connection. Repetition matters because financial capability usually develops through practice rather than one reading of a brochure.
This approach resembles experiential learning: people learn by acting, reviewing the result and adjusting future behaviour. A user who misses a bill because several small purchases reduced the available balance receives a real lesson in cash-flow planning. A responsible platform can make that lesson clearer without scolding the customer or turning the app into a classroom.
The best teaching moments often occur close to a transaction. A foreign exchange fee should be explained before a transfer is confirmed. The cost of credit should appear before a customer accepts it. A warning about an unusual recipient belongs on the payment screen, not in a help article hidden several menus away. Timing makes information useful.
Making Budgeting More Practical
A budget compares expected income with planned expenses during a chosen period. It helps a household allocate money among housing, food, transport, debt repayments, savings and optional purchases. The idea is simple, but maintaining a budget can be tedious. Payment apps reduce some of the administrative work by recording transactions automatically.
Many banking and wallet apps group spending into categories such as groceries, transport, utilities and entertainment. They may compare current spending with the prior month or allow users to set a category cap. This gives someone who has never used a spreadsheet a workable starting point.
Category data still requires judgement. Automated classification frequently gets transactions wrong. A supermarket payment may cover food, medicine and household goods, while a payment to an online retailer could represent almost anything. Transfers between a person’s own accounts may also look like income or spending unless the software recognises them correctly.
Users should be allowed to rename categories, split transactions and exclude internal transfers. A budget designed around personal circumstances has more educational value than a rigid template. Transport may be a fixed work expense for one person and an optional expense for another. Childcare, medical costs and support for relatives can also require categories that a standard app does not provide.
Fixed, Variable and Irregular Costs
Payment histories can teach the difference between fixed, variable and irregular expenses. Rent, insurance and loan payments are often predictable. Food, fuel and leisure costs vary. Annual insurance renewals, school supplies and vehicle repairs occur less often but can still place pressure on a monthly budget.
An app that displays only monthly averages can hide this pressure. Better tools show due dates and allow users to reserve money for annual or seasonal bills. Setting aside £50 each month for a £600 yearly expense teaches a basic planning principle: an infrequent bill is not necessarily an unexpected bill.
Budget tools can also show the difference between income and available cash. A worker may earn enough across a month but still face a shortfall if bills fall due before wages arrive. Calendar views, scheduled payment lists and balance forecasts can make this timing problem visible. That is cash-flow education in a very practical form.
| Platform feature | Financial lesson | Common caution |
|---|---|---|
| Automatic spending categories | Shows where money went over a week or month | Merchant categories may be inaccurate |
| Bill calendar | Connects payment dates with available cash | Unrecorded bills can distort the forecast |
| Category spending caps | Compares planned and actual expenses | A cap does not judge whether the plan is realistic |
| Balance alerts | Warns when funds may not cover near-term payments | Late alerts leave little time to respond |
| Monthly comparisons | Shows changes in habits and recurring costs | Seasonal expenses can make comparisons misleading |
Automated summaries describe past behaviour; they do not decide whether it was wise. A high food bill may reflect waste, a larger household or a temporary medical need. Users still need to consider income stability, dependants, local costs and future commitments. Software can organise the evidence, but human judgement remains part of budgeting.
Building Saving Habits and Financial Goals
Digital payment services can make saving easier to organise. Many let customers create separate pots, vaults or subaccounts for emergencies, education, holidays, tax payments and other goals. Separating funds reduces the chance that money reserved for one purpose will be mistaken for spendable cash.
Automatic transfers can also change saving from an occasional decision into a routine. A customer might move a set amount after payday, transfer a percentage of each incoming payment or round purchases up to the nearest pound. These methods teach that saving can happen before optional spending rather than after it.
Small transfers need proper context. Round-up features may help establish a habit, but they rarely build an adequate emergency reserve by themselves. A platform should show the actual amount accumulated and avoid overstating the likely result. Ten or twenty pounds a month can be useful, though it does not replace a plan based on income and likely expenses.
Progress Indicators and Time Frames
Goal trackers often display a target amount, current balance and expected completion date. These figures show the relationship between contribution size and time. If a customer wants £1,200 within a year, the platform can show that the plan requires about £100 per month before interest. Changing the target date makes the trade-off visible.
Goal features can also teach prioritisation. A household may be trying to build an emergency reserve, repay high-cost debt and save for a purchase at the same time. The app cannot settle every priority, but it can display how much money each goal receives and whether the plan fits available income.
Some services connect savings pots to interest-bearing accounts. This creates an opportunity to explain annual rates, compounding and variable returns. Plain examples work better than technical wording. A platform could show the estimated interest on the current balance while stating that a variable rate may change.
Product terms require equal attention. A high advertised rate may apply only up to a balance cap, for a short introductory period or after meeting deposit conditions. Withdrawal restrictions and account fees can reduce the benefit. Educational design should place these facts near the rate rather than burying them in lengthy terms.
Showing the True Cost of Credit
Many payment platforms now offer overdrafts, credit cards, cash advances, personal loans or buy-now-pay-later plans. Credit can help manage timing differences or pay for a necessary purchase, but its presentation strongly affects how customers judge affordability.
A low monthly instalment can make an expensive purchase appear manageable. The user also needs to see the amount borrowed, the number of payments, interest, fees and total repayment. If a promotional rate later changes, the platform should state when that will happen and what the new payment may be.
Good educational design answers practical questions before acceptance:
- How much will the customer repay in total?
- On which dates will payments be collected?
- What fee or interest applies after a missed payment?
- Can the customer repay early, and does that change the cost?
- Will repayment behaviour be reported to a credit bureau?
These questions should not require a hunt through several screens. Concise summaries can sit beside full legal terms, giving customers a readable account without removing formal disclosures.
Buy-Now-Pay-Later and Overlapping Commitments
Instalment services show why consolidated payment data has educational value. A single four-payment plan may look affordable. Five plans from different merchants can create a much larger obligation, especially when collection dates cluster around the same week.
A platform that shows all upcoming instalments on one calendar helps users assess the combined burden. It can also compare scheduled repayments with the expected balance. Such a display teaches that affordability depends on total commitments, not the cost of one purchase viewed alone.
Credit education should also cover consequences. Missed payments may lead to fees, collection activity, service restrictions or damage to a credit record, depending on local law and provider policy. The wording should remain factual. Threatening language rarely teaches well and may cause users to avoid opening notices that contain useful options.
There is a clear distinction between explaining credit and promoting it. Frequent pop-ups offering larger borrowing amounts can conflict with responsible education. A provider should not present a higher credit limit as proof of improved financial health. Greater access to debt increases purchasing capacity; it does not increase income.
Improving Access to Formal Financial Services
Mobile payments can bring financial records and account services to people who rarely use a branch. This is relevant for rural residents, migrants, informal workers, small traders and customers with irregular income. A mobile account may receive wages, benefits, remittances or customer payments while producing a history that can be reviewed at any time.
Regular account use introduces practical concepts such as available balance, pending payment, statement period, transfer reference and settlement time. These terms may sound basic to experienced bank customers, but they are part of the learning process for someone using formal services for the first time.
Digital records can also help workers document income. A self-employed driver or market trader who receives electronic payments may be better placed to show revenue to a landlord, lender or accountant. Yet transaction volume does not equal profit, and platform data may omit cash sales and business expenses paid elsewhere.
Access to an account should not be confused with full financial participation. A customer may own a smartphone but face expensive data, weak network coverage, identification barriers or low confidence with apps. Some people share devices or phone numbers, which raises privacy and account recovery concerns. Others may need local-language support or an interface compatible with assistive technology.
Digital financial education should account for these practical conditions. Instructions that assume constant internet access or private device ownership may fail the users who need support most. Offline receipts, low-data modes, clear recovery procedures and human customer service can all affect whether an account remains useful.
Developing Payment Security Skills
Financial education through payment platforms is closely connected to digital safety. A person may manage a sound budget and still lose money through phishing, impersonation, account takeover or an authorised payment scam. Security knowledge therefore belongs beside lessons on saving and borrowing.
Platforms can teach safe behaviour through prompts that appear during account use. A new-recipient warning can ask the sender to check the name and account details. A login notice can help the customer spot access from an unfamiliar device. Delayed high-risk transfers may give a user time to reconsider a payment requested by a fraudster.
Useful security education explains both procedure and reason. Telling customers never to share a one-time code is good; explaining that the code can authorise access or a payment is better. Users should know that a caller can sound professional, know personal details and still be fraudulent.
Common Skills Payment Users Need
Customers should know how to create a strong passphrase, activate device security and protect a personal identification number. They also need to check web addresses, avoid installing software at a caller’s request and contact the provider through an official channel. Payment confirmation screens deserve careful reading, especially where the recipient cannot easily return the money.
Scam warnings must stay current and concise. If every transfer produces a long generic warning, users learn to dismiss it. Risk-based prompts are more useful when they refer to the transaction at hand, such as a first payment to a new recipient or an unusually large transfer.
Customers also need a clear route for reporting mistakes and fraud. The platform should explain how to freeze a card, dispute a transaction and provide evidence. Response deadlines and refund rules vary by payment type and jurisdiction, so the app should not imply that every loss receives the same treatment.
Consumer Literacy at the Point of Payment
Payment screens influence how customers interpret prices. A purchase may include delivery charges, currency conversion, gratuities, recurring billing or optional insurance. Displaying the final amount before authorisation helps the user compare the quoted price with the actual charge.
Foreign exchange provides a common teaching case. A transfer service might advertise a low fee while applying an exchange rate that produces a higher total cost. Customers need both the fee and the amount the recipient will receive. Comparing providers becomes easier when each shows the same basic figures.
Subscriptions create another issue. Free trials can convert to paid plans, and annual billing may appear cheaper per month while requiring a larger payment upfront. Payment apps can identify recurring charges, show the next expected collection date and provide access to merchant contact details. They should not claim to cancel a contract unless they can actually do so.
Interface design can either support or weaken consumer choice. Preselected add-ons, faint decline buttons and confusing double negatives make consent harder to assess. Clear labels and balanced button placement are not cosmetic details; they affect whether a customer knows what they are buying.
Legal terms remain necessary, but few users read long documents during checkout. A short summary of price, renewal, cancellation and data use can sit above the confirmation button, with full terms available for review. Plain language is more educational than a wall of legal wording.
Transaction Data and Personal Feedback
Payment providers hold detailed records about where, when and how customers spend. With valid permission and proper safeguards, that data can support personalised feedback. An app might identify duplicate subscriptions, show that utility costs have risen or warn that current spending is above the user’s normal range.
Personal feedback often feels more relevant than broad financial advice because it relates to actual behaviour. A recommendation to review discretionary spending is vague. A notice showing £240 spent on unused memberships over six months gives the customer a concrete figure to assess.
Context remains necessary. An unusual rise in spending might reflect travel, a household emergency or delayed reimbursement from an employer. Automated systems do not always know the reason. They should present observations as prompts for review rather than definitive judgements.
Privacy and Permission
Payment data can reveal much more than shopping preferences. Transactions may indicate a person’s location, health, beliefs, relationships, employment and daily routine. Providers should state what data they collect, why they use it, how long they retain it and which parties receive it.
Permission should be meaningful. A customer should not have to approve broad advertising use merely to receive a basic spending summary. Settings should allow users to stop optional analysis without losing access to core payment functions where law and technical requirements permit.
Educational claims must not become an excuse for excessive monitoring. A provider may argue that detailed behavioural data helps customers manage money, yet the same data can support targeted credit marketing. Clear separation between guidance and promotion helps users judge whose interest a message serves.
Data accuracy also matters. Duplicate transactions, delayed refunds and incorrectly labelled merchants can produce faulty recommendations. Customers should be able to correct errors or flag them for review. Advice built on bad records is no bargain.
Financial Education for Small Businesses
Small business owners often learn financial management while operating the business. Merchant payment platforms can support that process by separating business receipts from personal spending and producing regular sales records.
A merchant dashboard may show daily revenue, refunds, transaction fees and settlement dates. These records introduce the distinction between sales and cash received. A business can make a sale on Monday but receive the funds on Wednesday after fees are deducted. That timing affects supplier payments, wages and stock purchases.
Digital records can also clarify the difference between revenue and profit. High transaction volume may look encouraging, but it says little about rent, materials, tax, labour and payment processing costs. Platforms should avoid labelling sales as earnings unless expenses have been accounted for.
Cash Flow, Fees and Settlement Delays
Cash flow often creates more immediate pressure than accounting profit. A business may be profitable across a quarter yet struggle to pay a supplier because customer receipts arrive later. Settlement calendars and expected deposit notices help owners plan around that gap.
Fees require clear reporting. Merchant service charges may include a percentage of each transaction, a fixed amount, monthly account fees, equipment rental or currency charges. A dashboard that separates these costs can help an owner calculate the true price of accepting each payment method.
Chargebacks and refunds also have educational value. A reversed transaction can remove revenue and add an administration fee. Providers should explain reserve requirements, evidence deadlines and the conditions under which funds may be held. Small traders need this knowledge before a dispute occurs, not after cash has disappeared from the account.
Organised payment records may support bookkeeping and tax preparation. They do not determine tax treatment, which depends on local rules and business structure. Owners still need to record cash sales, deductible expenses and payments handled outside the platform. Where needed, an accountant or qualified adviser should review the records.
Risks That Can Weaken Educational Value
Convenience can work against thoughtful money management. Stored card details, one-tap checkout and instant transfers remove friction from purchases. That saves time, but it also shortens the pause during which a customer might reconsider an optional expense.
Rewards and promotional notices can increase this effect. Cashback, streaks, badges and short-term discounts may encourage more transactions. Such features are not financial education simply because they appear beside a budget chart. A platform should assess whether its behavioural prompts support the customer’s stated goals or mainly increase spending.
Digital exclusion presents another risk. Older users, people with disabilities, customers with lower literacy and speakers of minority languages may struggle with small text, crowded screens or unfamiliar terms. Frequent interface changes can also create mistakes. Accessibility testing should include real users rather than rely only on technical compliance checks.
Service dependence deserves attention as well. Outages, frozen accounts, lost phones and failed identity checks can interrupt access to money. Users should know how to obtain support, recover an account and use another payment method where necessary. Keeping a modest backup payment option can form part of household resilience.
Fraud losses can undermine trust in all digital finance. Providers should maintain security controls, but customer education cannot shift the entire burden onto the user. If an interface allows risky payments without proportionate checks, a warning buried in the terms is not enough.
Responsibilities Across the Financial Education Process
Payment providers control the interface, records and transaction prompts. They should disclose fees, exchange rates, repayment terms and data practices before the customer commits. Educational material should remain distinguishable from advertising. A lesson about emergency savings should not end with pressure to buy an unsuitable investment product.
Schools and community organisations can use fictional payment histories in lessons. Learners might identify recurring charges, calculate instalment costs or compare a spending plan with actual transactions. This connects classroom concepts with situations people meet outside school.
Employers and public agencies also have a role when moving wages or benefits to digital accounts. New users may need help with account access, fees, cash withdrawal, fraud reporting and payment disputes. A short orientation can prevent common errors, especially where recipients did not choose the platform themselves.
Regulators set rules for disclosure, lending, privacy, accessibility and complaint handling. They can require providers to show total credit costs, give advance notice of fees and maintain fair dispute procedures. Supervisory work should examine what users actually see on screen, not only whether a disclosure exists somewhere in a document.
Independent consumer groups can test apps and explain common risks without a sales incentive. Their research may reveal whether fee displays are readable, cancellation routes work and support teams respond within stated times. This external scrutiny gives educational claims a reality check.
Measuring Whether Users Actually Learn
The presence of a spending chart does not prove that financial capability has improved. Evaluation should examine whether users interpret the data correctly and make better-informed decisions over time.
Knowledge measures may test whether customers can identify the total cost of credit, compare exchange rates or recognise a fraudulent payment request. Behavioural measures may examine budgeting accuracy, emergency saving, missed repayments and cancellation of unwanted subscriptions.
Researchers should also consider distribution. An app may help users with stable incomes but offer little benefit to people whose earnings change sharply each week. Results can differ by age, disability, language, income and prior banking experience. Average results can hide groups that receive no benefit or experience harm.
Unintended outcomes require attention. A platform might increase savings while also encouraging greater overdraft use. Digital records may improve budgeting while exposing more personal data. Fast transfers can lower remittance costs but raise the impact of scams. Several measures are needed to assess education fairly.
Longer observation often provides better evidence than a short trial. A user may respond to a new budgeting feature for a few weeks and then stop checking it. Lasting improvement involves habits that continue after the novelty fades.
Future Direction of Payment-Based Learning
Payment services are likely to combine data from more accounts where local law permits and the customer authorises access. A single view of bank accounts, cards, savings and loans could help users assess their full financial position. It could also create a richer privacy target, so permission controls and security standards will need equal attention.
Automated assistants may explain transactions in conversational language, answer questions about fees and model the effect of repayment choices. Such tools can make financial terms easier to use, but they may also produce incorrect or inappropriate guidance. Providers should show the assumptions behind calculations and offer a route to human support.
More education may appear directly within payment flows. A transfer screen could explain an exchange-rate margin before confirmation. A credit screen could compare two repayment periods. A subscription notice could show the annual cost rather than only the monthly charge. Short, timely explanations often serve users better than a separate learning centre they may never open.
Future systems may also let customers choose the type and frequency of guidance they receive. One person may want weekly summaries, while another prefers alerts only when a balance may not cover scheduled bills. User control can reduce notification fatigue and make prompts more relevant.
What Responsible Digital Financial Education Looks Like
A responsible payment platform gives users a clear account of what has happened, what a proposed action will cost and what obligations follow. It makes records easy to correct, distinguishes education from promotion and treats privacy as part of financial wellbeing.
Such a platform does not assume that more activity is always better. Its educational success should be judged by better awareness, safer decisions and stronger control over money, not transaction volume alone. Sometimes the most useful prompt will lead a customer not to borrow, not to renew or not to send a payment.
Digital payment services cannot replace schools, community programmes, professional advice or fair regulation. They can, however, place practical financial guidance beside the moments when people receive wages, pay bills, save money and take credit.
The strongest model combines accurate transaction data, plain explanations, accessible design, proportionate security and honest product disclosure. Used with care, payment platforms can turn routine financial activity into repeated learning. Used poorly, they can make spending and borrowing easier without making users any wiser. The difference lies less in the technology than in the choices made by the organisations that design, regulate and teach through it.