Teaching children about money in Chinese families involves far more than identifying coins, reading prices, or practising arithmetic. Financial education also touches on saving, educational spending, work, generosity, family duty, social customs, and support for older relatives. A useful approach respects these cultural ideas while giving children room to form independent financial judgments.
Chinese families do not follow one financial model. Practices vary across mainland China, Hong Kong, Taiwan, Singapore, Malaysia, and Chinese communities elsewhere. Income, migration history, religion, housing costs, urban or rural life, and the experiences of parents and grandparents all affect how a household treats money. Some parents speak openly about income and bills. Others regard financial matters as private adult business.
Many families share a preference for financial security, careful spending, educational investment, and assistance between relatives. These values offer a practical basis for teaching children, but financial caution should not become fear. The goal is not to produce a child who refuses to spend. It is to raise someone who can plan, compare choices, recognise risk, and manage obligations without losing personal independence.
Begin with ordinary household decisions
Young children learn about money by watching adults buy groceries, pay restaurant bills, order products online, and decide that some purchases can wait. These everyday moments are often more useful than a formal lecture because the child can connect the idea to something visible.
At a supermarket, a parent can compare package sizes and unit prices. At a market, the child can see how quality, season, and quantity affect cost. During an online purchase, an older child can check delivery fees and return conditions before the family pays. The lesson is not always to choose the cheapest option. A cheaper item that breaks quickly may offer poor value, while a dearer product may be worth buying if it lasts longer or serves a regular need.
Parents can also explain spending choices in plain language. A statement such as, “We can buy the larger toy or keep the money for your school trip, but we will not pay for both this week,” presents a real trade-off. It avoids making the child responsible for the household’s finances, yet shows that income has competing uses.
Repeated exposure matters. A five-year-old may only grasp that two items cost more than one. A ten-year-old can compare prices and calculate change. A teenager can assess subscription fees, delivery costs, warranties, and cancellation rules. The same shopping trip can teach a different lesson at each age.
Explain where household money comes from
Children often see adults pay for goods without seeing the work, planning, and deductions behind that payment. Cash appears from a wallet, while digital payments may look like a tap on a screen. Parents can correct this impression by explaining that households usually receive money through wages, business income, pensions, investment income, public benefits, or transfers from relatives.
A basic explanation of gross and net pay can begin during the teenage years. Gross pay is the amount earned before deductions. Net pay is what reaches the worker after tax, pension contributions, insurance, or other deductions. This helps teenagers interpret job advertisements more accurately. A salary figure is not the same as spendable monthly income.
Parents who own a shop, restaurant, farm, trading company, or home-based business can explain the difference between sales and profit. If a restaurant takes in a certain amount during dinner service, that money must still cover food, rent, wages, utilities, payment fees, licences, and tax. Revenue may look impressive while the remaining profit is modest. This is a useful correction to the common idea that every payment received by a business belongs to its owner.
Families do not need to disclose every account balance. A general explanation is enough for younger children. As they mature, they can learn more about regular bills, irregular costs, and the need to keep money available for emergencies.
Teach saving without creating financial fear
Saving holds a respected place in many Chinese households. Parents or grandparents may have experienced shortages, migration, unstable employment, medical expenses, or periods when several generations depended on one income. Their caution often comes from experience rather than simple reluctance to spend.
Children should still learn that saving is a tool, not a measure of moral worth. Spending on food, healthcare, transport, education, rest, and reasonable recreation is part of normal life. A child who hears only warnings may begin to hide purchases, feel guilty about necessities, or avoid asking for help after making a mistake.
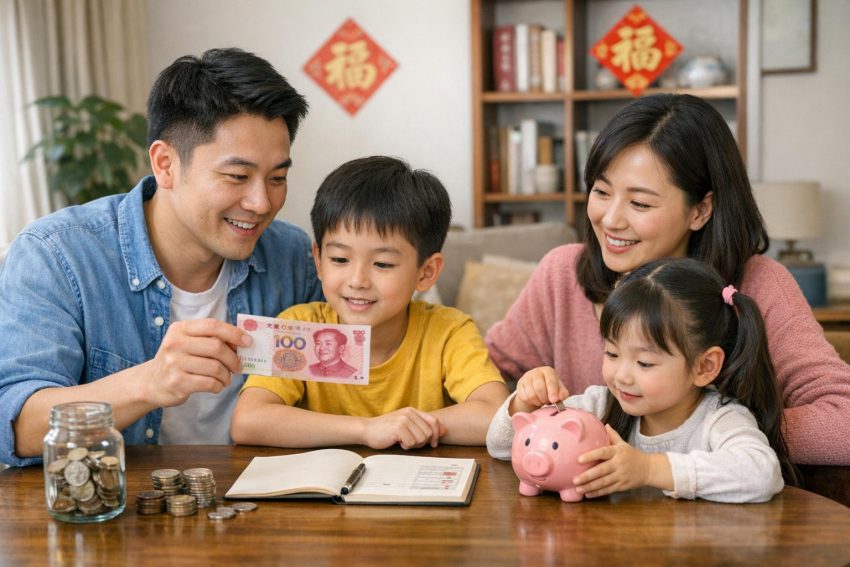
A clear framework is to divide money among current needs, future plans, and giving or family duties. Younger children may use labelled jars or envelopes. Older children can use a notebook, spreadsheet, or supervised banking application. The percentages need not be equal. A child saving for a bicycle may direct most gift money to that goal for several months.
Goal-based saving makes the idea concrete. If an item costs 600 yuan, dollars, or another local currency, and the child saves 50 each month, the target will take about twelve months without other contributions. The family can then discuss whether the goal remains worthwhile, whether a used item would meet the need, or whether the child could earn part of the cost through suitable paid work.
Emergency saving can be introduced later. A teenager does not need a full adult emergency fund, but keeping some money uncommitted teaches a useful habit. A broken phone screen, missed bus, or school expense is less disruptive when every coin has not already been assigned.
Use allowances as practice money
There is no single correct allowance system. Some parents provide money only after a child asks and explains the purchase. Others give a regular weekly or monthly amount. Either method can teach good habits if the rules are predictable.
A regular allowance gives the child repeated budgeting practice. It should cover clearly defined categories, such as snacks, small toys, entertainment, or gifts for friends. Parents should state which costs remain their responsibility. A teenager cannot budget sensibly if one month the allowance covers transport and the next month it does not.
The payment period should suit the child’s age. Younger children usually manage a weekly amount more easily. Teenagers may benefit from a monthly amount because it requires them to plan across a longer period. Parents can begin with fewer spending categories, then add transport, clothing, phone costs, or social activities as the teenager becomes more capable.
| Age range | Possible allowance period | Skills to practise |
|---|---|---|
| 5–7 | Weekly | Counting, waiting, choosing one item over another |
| 8–11 | Weekly or fortnightly | Recording purchases, saving for a goal, checking change |
| 12–15 | Fortnightly or monthly | Budgeting for snacks, gifts, transport, and entertainment |
| 16–18 | Monthly | Managing phone costs, clothing, work income, and irregular expenses |
Running out of allowance can become a useful lesson if the consequence remains safe and proportionate. A child who spends the week’s snack money on the first day may need to bring food from home for the rest of the week. Parents should not allow a budgeting mistake to prevent access to lunch, necessary transport, medicine, or school materials.
Automatic replacement weakens the lesson. A calmer response is to review the record, identify what went wrong, and adjust the next budget if the original amount was unrealistic. Sometimes the problem is impulsive spending. Sometimes the amount does not match the expenses parents expect the child to cover.
Separate family chores from paid work
Many families debate whether children should earn money for chores. Paying for every task can make ordinary cooperation feel like a commercial exchange. Refusing payment for substantial work can also be unfair, particularly when a child contributes to a family business.
A practical distinction is to treat routine household duties as membership responsibilities. Making the bed, putting away clothes, washing one’s dishes, and helping set the table may fall into this category. Extra work outside the child’s normal role may receive payment. Washing the family car, organising old stock, translating a short document, or helping at an event could qualify, depending on age and effort.
Work in a family restaurant, store, farm, or office requires more care. Parents should explain the hours, duties, payment, and expectations before the work begins. Older children may learn about time sheets, wages, customer service, stock control, and operating costs. Local rules on child employment, working hours, safety, and school attendance still apply to family businesses.
Children should also learn that unpaid labour has economic value. Cooking, cleaning, childcare, elder care, and household administration keep a family functioning. Treating paid employment as the only useful work can reinforce unfair gender roles and cause children to overlook what relatives contribute at home.
Connect education costs with informed choices
Education receives a large share of spending in many Chinese households. Costs may include school fees, tutoring, examination preparation, music tuition, language classes, technology, university accommodation, or overseas study. Parents often make sacrifices to provide these opportunities, but children should not be taught that their worth depends on producing a high financial return.
Older children can take part in evaluating educational expenses. Before enrolling in a course, the family can discuss its purpose, schedule, price, teaching quality, and likely benefit. Does the child need help with a weak subject, or has tutoring become automatic because classmates attend? Is a costly course the best choice, or would school support and regular practice achieve the same result?
This conversation also helps children respect family spending without turning gratitude into a debt contract. Parents may reasonably expect effort, attendance, and honest feedback. They should be cautious about saying that paying for education gives them permanent control over a child’s occupation, partner, income, or place of residence.
Teenagers considering university can compare tuition, housing, transport, books, scholarships, part-time work, and likely borrowing. Career earnings matter, but they are not the only factor. Working conditions, job availability, health, aptitude, and personal interest also affect whether an education plan makes sense.
Handle red-envelope money as a learning opportunity
Red envelopes, called hongbao in Mandarin and lai see in Cantonese, give families a natural opening for money lessons. Children may receive them during Lunar New Year, birthdays, weddings, or other family events. Digital red envelopes are also common in parts of Asia.
Parents can ask children to count the money, record who gave it, and decide how it will be used. A younger child may choose a small purchase and save the rest. A teenager may assign part to a longer goal, part to current spending, and part to a family or charitable purpose.
Some parents take all red-envelope money for safekeeping. That may be reasonable for a very young child or a large amount, but the arrangement should be explained. The child should know whether the money is being deposited in an account, used for education, or managed on the child’s behalf. Saying, “I will keep it for you,” without any later record can cause mistrust.
A simple red-envelope record can include the date, amount, giver, deposit, and any approved spending. This does not need to become formal accounting. Its purpose is to connect the custom with ownership, record-keeping, and planning.
Children should also learn the social meaning of the exchange. Publicly comparing amounts may embarrass relatives or turn goodwill into competition. The sum varies according to relationship, local custom, and family finances. Courtesy does not require pretending money has no value, but it does require treating the giver respectfully.
Discuss giving, reciprocity, and social spending
Money in Chinese social life may involve wedding gifts, festival gifts, meals, visits, funeral contributions, and assistance during illness. Children may see adults keep records of gifts received and given. Parents can explain that these practices often express care, reciprocity, respect, and continued connection.
Reciprocity should not be taught as a rigid calculation. Families sometimes give more because another household faces hardship, and sometimes they give less because their own budget is tight. A gift should not require unaffordable borrowing simply to protect appearances.
Teenagers benefit from learning how social pressure affects spending. They may feel pushed to buy costly birthday presents, pay for group meals, or copy classmates’ clothing and devices. Parents can help them set a gift budget and suggest alternatives, such as sharing costs with friends or choosing a thoughtful lower-priced item.
Charitable giving can be handled in the same practical manner. A child may choose a cause, check how the organisation uses donations, and give an affordable amount. Generosity and financial judgment are compatible. Giving away money needed for food, housing, or debt payments is not responsible generosity.
Discuss family obligations in clear terms
Support for parents and grandparents forms part of family life in many Chinese households. Adult children may contribute to housing, medical care, daily expenses, or retirement. Migrant families may also send money to relatives in another city or country.
Children can learn that helping relatives matters, while also learning that obligations require discussion. Vague statements such as “You will support everyone one day” can create anxiety without teaching any practical method. Older teenagers and young adults need clearer information about what parents expect, what retirement resources exist, and how siblings may share costs.
Financial help between adults should be identified as a gift, loan, or shared expense. Each category has different consequences. A loan should include an amount, repayment plan, and response if repayment becomes difficult. Writing down the agreement may feel formal, but it often protects the relationship. Memory becomes strangely flexible where family money is concerned.
Parents should also explain that helping does not require accepting every request. A relative may ask for money for medical treatment, business investment, gambling debt, or an unverified scheme. Each request carries a different level of need and risk. Saying no, offering a smaller amount, paying a bill directly, or providing non-financial help may be appropriate.
Children should never be used as messengers in adult financial disputes. Nor should they be told that they caused money problems through ordinary needs. Adults remain responsible for household decisions even when children are invited to contribute ideas.
Introduce bank accounts and interest
A supervised savings account can help an older child connect records with real money. Availability depends on local law and bank policy, but many institutions offer youth accounts controlled or monitored by a parent or guardian.
Children should learn how to read the account name, balance, deposits, withdrawals, fees, and interest entries. They should know that the displayed balance may include money already committed to a pending purchase. They should also check statements for unfamiliar transactions instead of assuming the bank record must be correct.
Interest can be explained as either money earned on savings or money paid for borrowing. If a bank pays interest, the balance may grow over time. The rate, account rules, tax treatment, and inflation affect the real benefit. A small numerical exercise often works better than a long explanation.
Compound interest means interest may later be earned on earlier interest. Teenagers can compare how a balance changes under different rates and time periods. They should also learn that investment returns do not behave like guaranteed savings interest. Values may rise or fall, and fees can reduce gains.
Make digital payments visible
Mobile wallets, bank cards, transport cards, and online accounts can make spending feel detached from physical money. A child sees a phone scan or tap, but not the reduction in the account. Parents can restore that connection by reviewing transactions after a shopping trip.
Ask the child to match each receipt with the payment record. Include delivery fees, service charges, tips, foreign-exchange charges, and refunds. This teaches that the advertised price may not be the final amount paid.
Children who use a supervised card or wallet should have agreed spending rules. These may cover daily caps, approved merchants, in-app purchases, cash withdrawals, and what to do if the device or card is lost. Parents should explain monitoring openly rather than checking in secret. The child needs to know which transactions adults can see.
In-app purchases deserve close attention. Games and social platforms may use tokens, points, or virtual gifts that hide the cash value. Before approving a purchase, the child should convert the virtual amount back into local currency. A few small taps can produce a rather adult-sized bill.
Teach scam prevention and account security
Financial safety should begin before children receive independent access to payment accounts. They must never share passwords, one-time verification codes, identity numbers, card security codes, or account recovery answers with friends, callers, or message senders.
Common scams include fake delivery notices, impersonation of relatives, false police or bank calls, sham part-time jobs, counterfeit shopping sites, romance scams, and investment offers promising unusually high returns. Fraudsters often create urgency by claiming that an account will close, a relative is in danger, or payment must be made at once.
A useful household rule is to stop, leave the message untouched, and verify the request through a separate channel. If someone claims to be a relative, call that person using a saved number. If a message claims to come from a bank, use the official application or the number printed on the card. Do not use contact details supplied by the suspicious sender.
Parents should model the same habits. Forwarding unverified financial rumours, allowing another person to use one’s bank account, or sharing verification codes teaches the opposite lesson. Children notice inconsistencies with remarkable efficiency.
Explain debt and credit before children need them
Debt is neither automatically irresponsible nor automatically productive. Its effect depends on the purpose, cost, repayment period, contract, and borrower’s ability to pay. A mortgage, education loan, business loan, credit-card balance, and gambling debt should not be treated as equivalent.
Teenagers can learn the basic vocabulary of borrowing: principal, interest rate, repayment term, late fee, collateral, and default. They should know that a low monthly payment can hide a high total cost if the loan continues for many years.
Credit cards require careful explanation because they can look like extra income. They are a short-term loan. Paying the full statement balance by the due date may avoid interest in many systems, but cash advances and some transactions follow different rules. Paying only the minimum can keep a balance alive for years.
Buy-now-pay-later services also divide a purchase into smaller amounts, which can make the item appear cheaper. The true price has not changed. Several payment plans running at the same time can become difficult to track, especially when late fees apply.
Parents who have debt need not hide its existence, though children do not require every detail. A calm explanation of why the borrowing occurred and how repayments fit into the budget can prevent debt from becoming either shameful or casual.
Introduce investing with restraint
Older teenagers may become interested in shares, funds, property, gold, foreign currency, or digital assets. Social media often presents investing as rapid income rather than long-term ownership and risk. Parents can begin with the distinction between saving, investing, and speculation.
Savings generally prioritise access and stability. Investing accepts price changes in the hope of growth or income over time. Speculation relies more heavily on short-term price movement and may carry a greater chance of loss.
Before using real money, a teenager should be able to explain diversification, fees, taxes, time horizon, inflation, and the chance of losing part or all of an investment. They should know who regulates the provider and how money can be withdrawn. If the product cannot be explained in ordinary language, the child is not ready to buy it.
Property also requires balanced discussion. Home ownership may provide stability and long-term value, but it involves deposits, interest, maintenance, taxes, transaction costs, and price risk. A family’s past success with property does not guarantee the same result for the next generation.
Address gender expectations and financial fairness
Traditional roles can shape what boys and girls are taught about money. Sons may hear that they must buy housing or support parents. Daughters may be directed toward household budgeting while being excluded from investment or business discussions. Such divisions leave both groups with gaps in knowledge.
All children should learn budgeting, banking, tax basics, contract reading, negotiation, household costs, caregiving costs, and investment principles. Boys need experience with food budgets and domestic work. Girls need direct access to information about property, pensions, insurance, and business ownership.
Fairness between siblings also requires explanation. Equal support does not always mean identical payments. One child may have medical costs, another may receive university assistance, and another may be paid for regular business work. Parents can explain the reasoning without disclosing private details.
However, cultural preference should not be used to deny one child education, property rights, inheritance information, or control of personal earnings. Children should know which money belongs to them and which household rules govern its use.
Teach advertising and consumer judgment
Children encounter advertising through video platforms, games, influencers, live-stream shopping, and school friends. They should know that advertising aims to produce a purchase, even when it appears as entertainment or personal advice.
Parents can ask simple questions: Who is selling the product? Was the reviewer paid? Is the discount based on a genuine earlier price? Are reviews independent? What is the return policy? These questions turn passive viewing into consumer judgment.
Scarcity messages such as “only two left” or countdown timers may pressure buyers to act. Sometimes the claim is accurate; sometimes it resets after the page reloads. A waiting rule can help. Small discretionary purchases might require a 24-hour pause, while costlier items may require several days and a price comparison.
Brand names also deserve calm discussion. Some branded goods offer better materials, service, or resale value. Others cost more mainly because of status and marketing. Children can learn to assess function, durability, repairability, and total ownership cost rather than assuming either that brands are always superior or always wasteful.
Adjust financial lessons by age
Preschool children can identify coins and notes, practise waiting, and choose between two affordable items. Play shops help with counting, though real purchases make the connection clearer. At this stage, the lesson should remain short and concrete.
Primary-school children can receive a small allowance, keep a simple spending record, compare prices, and save for a chosen goal. They can read receipts and learn that advertisements are designed to influence them. Parents can introduce the idea that lost or damaged possessions cost money to replace.
Early adolescents can manage budgets for snacks, transport, entertainment, and gifts. They can calculate discounts, check mobile-payment records, and learn how subscriptions renew. This is also a suitable period for scam awareness and rules about in-app purchases.
Older teenagers can study payslips, tax deductions, bank accounts, rent, insurance, employment contracts, borrowing, and education costs. They can prepare a monthly budget for living away from home, including food, utilities, transport, phone charges, medical costs, and an emergency reserve.
Age is not the only measure. One fourteen-year-old may manage a monthly allowance well, while another needs weekly guidance. Parents can increase independence after the child shows reliable record-keeping, safe online behaviour, and a willingness to discuss mistakes.
Use family meetings without transferring adult stress
A short family meeting can help with shared financial plans. The household may discuss a holiday budget, a new appliance, festival spending, or ways to reduce unused subscriptions. Children can offer ideas and see how adults compare priorities.
Parents should retain responsibility for adult decisions. Children may know that the household is reducing spending after a job loss, but they should not feel responsible for restoring the family income. An age-appropriate explanation could state that income has fallen, some purchases will be postponed, and adults are managing the required payments.
Money disagreements between parents should not be conducted through children. Nor should one parent ask a child to hide purchases from the other. Such behaviour links financial secrecy with loyalty and places the child in an unfair position.
Healthy communication includes admitting mistakes. A parent might say that a purchase was poorly researched or that a fee was missed. This shows that responsible adults do not avoid every error; they identify it, correct what they can, and change their process.
Balance privacy with openness
Financial education does not require parents to disclose salaries, account passwords, business records, or debts before a child is ready. Privacy protects the household and respects adult boundaries. Total secrecy, however, can leave young adults poorly prepared.
By the time a child approaches independent living, they should know how to pay bills, store documents, compare accounts, read a contract, contact a bank, and respond to fraud. They should also know whether parents expect future financial support and whether education assistance is a gift or loan.
Families can decide what information is shared at each age. Younger children may hear that housing, food, transport, and school all cost money. Teenagers may see a sample household budget with rounded figures. Young adults may take part in retirement, insurance, inheritance, or caregiving discussions that affect them directly.
The strongest financial education is gradual, practical, and culturally aware. Chinese family values such as thrift, educational commitment, respect for elders, and mutual support can work well beside independent judgment and personal boundaries. A child who records red-envelope money, compares prices, questions suspicious payment requests, and discusses family duties openly is learning more than how to save. That child is learning how money affects daily choices, relationships, work, and future security.